
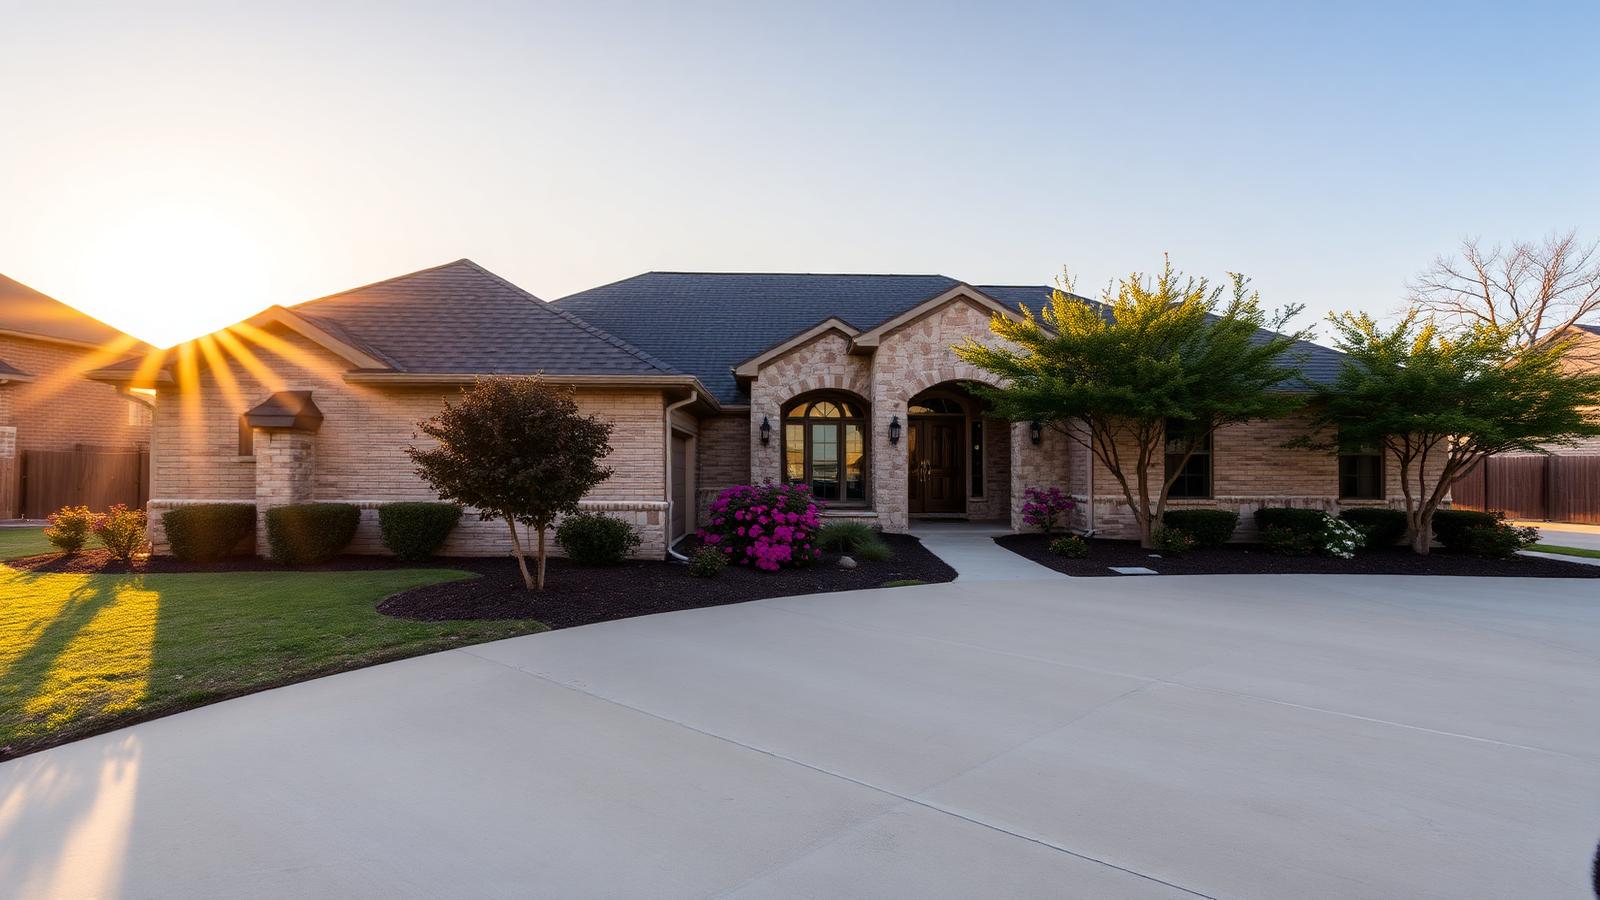

Local insights / Luling, LA
Luling’s housing market: insurance costs, cash buyers, and seller financing
US 90 and the Hale Boggs Memorial Bridge connect Luling’s west-bank neighborhoods to jobs and services across St. Charles Parish and the wider New Orleans area. For owners here, a sale often turns on practical details: the house’s condition, its flood exposure, what insurance will cost, and whether the buyer needs mortgage approval.
From established subdivisions to larger west-bank lots
Luling’s housing stock includes established brick-veneer ranch homes, older wood-frame houses, and newer subdivision properties. Lot size, drainage, roof condition, and renovation history can make two nearby homes very different purchases. Properties around the US 90 corridor also offer a different setting from homes closer to River Road and the Mississippi River.
Price comparisons should start with nearby properties of similar age, size, condition, and flood exposure, not Louisiana’s statewide median home value. For an older Luling home, documented roof work, foundation repairs, and updated electrical or plumbing systems can help buyers understand the asking price instead of assuming every unknown requires a discount.
Buyers weigh bridge access against repair and holding costs
Luling can attract owner-occupants seeking access to St. Charles Parish’s industrial employment corridor, along with investors evaluating rentals and renovation projects. I-310 and the Hale Boggs Memorial Bridge make access to both banks relevant, but investors still need property-level numbers: repair costs, likely rent, insurance, taxes, and resale prospects.
New Orleans-area investors are a natural audience for a Luling listing. Buyers based in Baton Rouge or Lafayette may also consider a property, but their interest and coverage area need to be confirmed. On Home Posted, owners can list free to reach pre-screened investors and cash buyers searching the Luling area, as well as request a direct cash offer. Neither route guarantees an offer or a particular price.
Flood documentation can matter as much as the inspection
Flood-zone questions, prior water intrusion, roof condition, and insurance availability can delay a financed sale. A mortgage buyer may need acceptable coverage before the lender will approve closing. In Luling, do not assume a property's risk from its distance to the Mississippi River alone; buyers should check the specific address, drainage history, and available flood records.
Some cash investors are willing to buy properties that need repairs or have costly insurance, but those issues do not disappear. Buyers may price the risk into their offer, request more documentation, or decline the purchase. Sharing known issues early reduces the chance of a late price renegotiation.
Title problems can create a separate delay, particularly with inherited property, unresolved successions, liens, or missing ownership documents. Assemble what you have before choosing a closing date, and ask a Louisiana title professional or attorney what remains to be cleared.
- Gather insurance declarations and any available flood or elevation documents.
- Record known flooding, repairs, permits, and roof replacement details.
- Obtain mortgage payoff information and identify any other recorded liens.
Cash now or payments over time?
A cash offer may suit an owner who needs sale proceeds promptly or does not want to keep managing repairs and carrying costs. Compare the net proceeds, not just the headline price, and review inspection rights, cancellation terms, proof of funds, closing costs, and the proposed closing date. A closing in as little as seven days may be possible for a straightforward transaction, but title work, payoff requirements, and buyer readiness can prevent that schedule.
Owner financing means receiving some of the purchase price over time rather than all at closing. It may broaden the buyer pool, but it leaves you exposed to missed payments and the work and expense of enforcing the agreement. A larger stated price is not necessarily a better outcome once payment risk, insurance obligations, and delayed access to your money are considered.
Before offering financing, have a Louisiana real estate attorney review the structure, any existing mortgage restrictions, required disclosures, and default provisions. A tax professional can explain the tax consequences. Owner financing should be a deliberate lending decision, not a last-minute substitute for a buyer who cannot close.
A foreclosure deadline needs more than a signing appointment
Louisiana foreclosure is judicial, and executory process can move more quickly than an ordinary lawsuit when its requirements are met. A general estimate of 60–120 days is not a reliable deadline for an individual seller. Notices, court filings, and a scheduled sheriff’s sale matter more than a broad timeline; contact a Louisiana foreclosure attorney promptly if you have received papers.
Louisiana closings commonly involve notarized documents, but it is too simple to say that you only choose a notary and show up. Title companies and attorneys can coordinate title examination, payoffs, funds, and recording, while the appropriate notarial formalities are handled at signing. Confirm who is responsible for each step and how recording in St. Charles Parish will be handled.
Requesting a cash offer or signing a purchase agreement does not itself stop foreclosure. Tell the closing professional about any pending sale date immediately, and have your attorney confirm what must happen to resolve the foreclosure before relying on a proposed fast closing.
Common questions
Can I list my Luling property free for local investors?
Yes. You can list for sale by owner free on Home Posted to reach pre-screened investors and cash buyers searching Luling and the surrounding area. Include photos, condition details, known flood history, and your preferred timeline. You can also request a direct cash offer.
Will a cash buyer purchase a Luling home with flood or insurance issues?
Some will consider it, but acceptance is not automatic. Cash buyers may have more flexibility than mortgage-dependent buyers, while still accounting for insurance costs, repairs, and future resale risk in their offer.
Is owner financing better than taking a cash offer?
It depends on whether you need proceeds now and whether you are willing and able to take on lending risk. Compare the down payment, payment schedule, expected net return, and consequences of default with the certainty and net proceeds of a cash closing. Have a Louisiana attorney review any financing arrangement before committing.
Can a Luling sale close in seven days?
It may be possible with a ready cash buyer, clear title, available payoff information, and completed closing documents. Inherited ownership issues, liens, or an approaching foreclosure sale can complicate that schedule. Get a property-specific timeline from the professional coordinating the closing.
Does a notary handle everything at a Louisiana closing?
Not necessarily. Notarization is important, but title review, lien resolution, disbursement, and recording are separate tasks. Ask the closing provider who handles those responsibilities and whether an attorney is needed for any ownership or foreclosure issues.
List your house in Luling, LA, free, with no percentage commission
Buyers search in Luling, LA every day. Put your property in front of them, choose the offer types you will consider, and manage conversations in the platform.
- No listing fee or percentage commission
- Seen by buyers and investors