
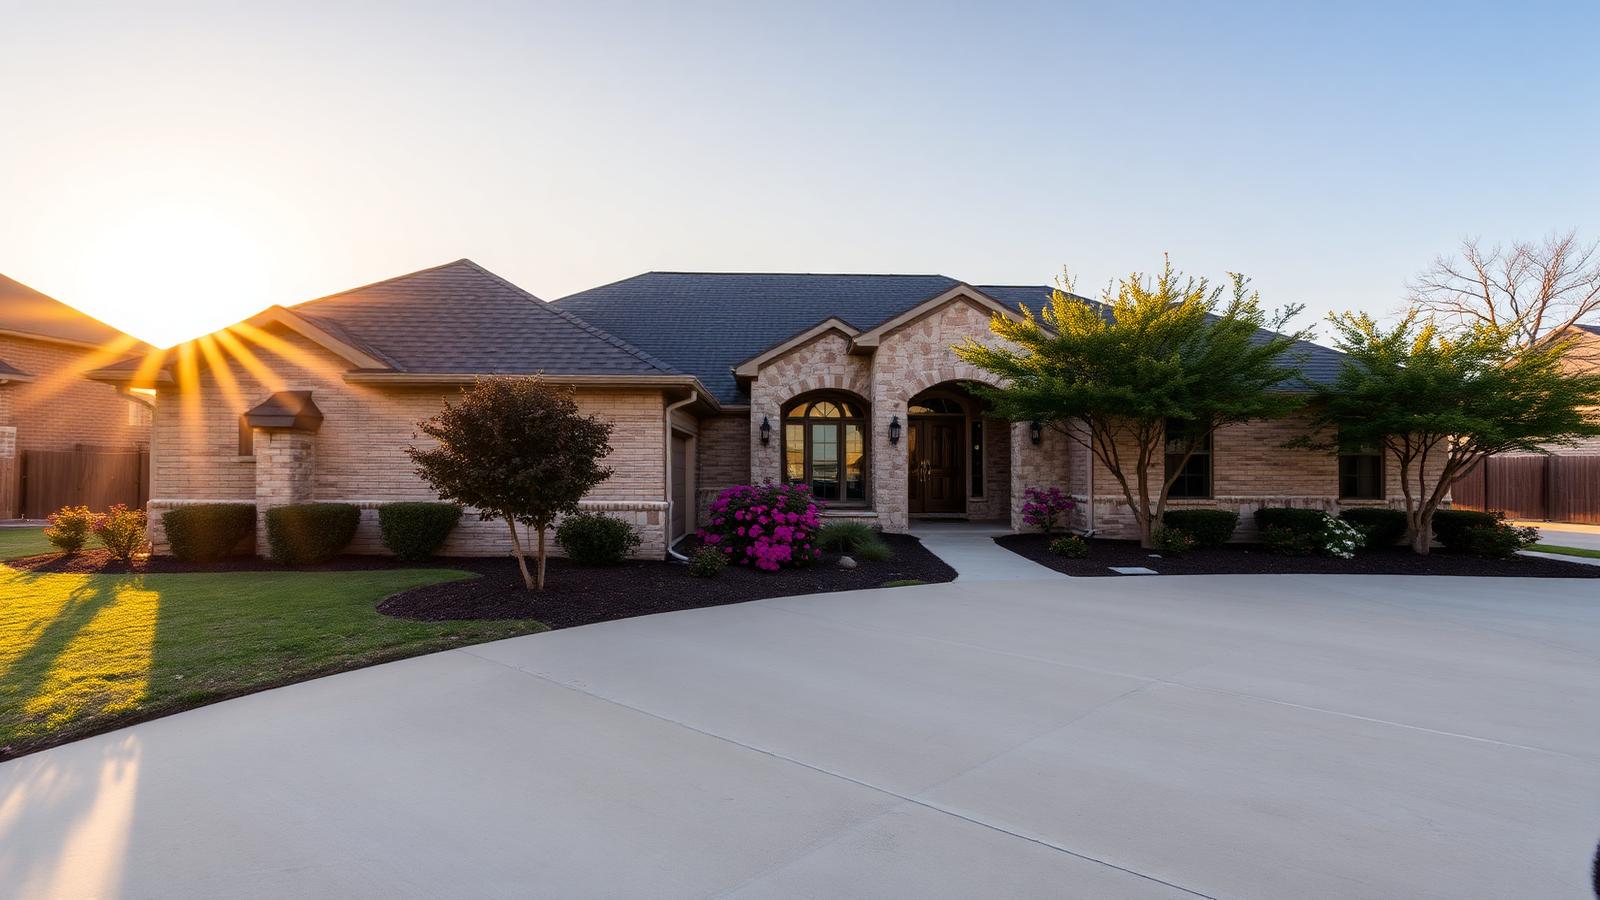

Local insights / Broussard, LA
Broussard homes: weighing cash offers against owner financing
U.S. 90 connects Broussard to Lafayette’s job market and the industrial businesses along the corridor. That access matters to buyers, but so do a home’s age, drainage history and insurance costs. For owners choosing between a cash sale and payments over time, the useful comparison is not just the sale price, it is the money available at closing, the obligations that remain and the risk of delays.
Older homes and newer subdivisions need different pricing
Broussard’s housing includes older homes near its historic center and newer subdivision houses farther out. Around the LA 182 corridor, an older property’s roof, electrical system and previous repairs may shape an investor’s budget. For a newer house, competing listings, homeowners association requirements and the cost of insurance can matter just as much as its finishes.
Access to Lafayette, U.S. 90 and amenities such as St. Julien Park helps explain why buyers consider Broussard, but those advantages do not establish a particular home’s value. Louisiana’s statewide median is too broad to price a local property. Compare nearby homes with similar age, size, condition and flood exposure rather than applying one statewide number.
The buyer pool starts with Lafayette-area demand
Owner-occupants may be looking for access to Lafayette employment or businesses tied to the region’s energy and service industries. Investors approach the same homes differently: rental buyers weigh likely rent against maintenance and insurance, while renovation buyers need enough room in the purchase price to cover repairs and resale costs.
Lafayette-area investors are a natural audience for a Broussard listing. Buyers based in Baton Rouge or New Orleans may also consider the property, but their location alone does not establish interest or ability to close. Ask about their experience with comparable properties, proof of funds and whether the purchase depends on financing or assignment to another buyer.
Flood exposure can change the deal after the showing
In the Lafayette Parish area, flood-zone status, drainage history and insurance availability deserve attention before a contract is signed. A buyer using a mortgage may face lender insurance requirements or repair conditions. Roof age, prior water intrusion and an unexpectedly high insurance quote can force a buyer to reconsider the monthly cost.
Cash buyers do not have mortgage underwriting requirements, but they still assess flood and insurance risk. Some will account for it in their price; others may decline. Sharing accurate condition information early gives interested buyers a better basis for an offer and reduces the chance of a late price change.
- Gather available flood-zone information, any elevation certificate and records of prior water damage or repairs.
- Make roof age, insurance information and known drainage problems available for review.
- Identify mortgages, liens, succession issues or missing ownership documents before setting a closing date.
Cash ends the payment relationship; owner financing extends it
A cash offer is usually the more direct option when you need sale proceeds at closing or want to avoid collecting payments after the sale. Compare the net amount after mortgage payoff, closing charges and any agreed deductions, not just the headline offer. A closing in as little as seven days may be possible, but title work, payoff information and the buyer’s readiness can take longer.
Owner financing means accepting some of the purchase price over time. It may expand the pool of potential purchasers, but it leaves you exposed to missed payments and the work of enforcing the agreement. Before agreeing, have a Louisiana real estate attorney review the proposed structure, any existing mortgage restrictions, security documents and default provisions. A tax professional can explain the tax consequences.
- Compare cash available at signing with the amount deferred under owner financing.
- Assess the proposed down payment, payment schedule and any balloon payment.
- Decide who will service payments and monitor insurance and property-tax obligations.
Set the closing date around the paperwork, not a promise
Louisiana conveyances commonly involve notarized documents, but choosing a notary and showing up to sign is not the whole closing process. Title examination, mortgage payoffs, lien resolution, funds handling and recording still need coordination. Confirm who is handling each step with a local closing professional; attorneys and title companies may also be involved.
Owners can list a Broussard home or land parcel free on Home Posted to reach pre-screened investors and cash buyers searching the area, or request a direct cash offer. If foreclosure is involved, tell the closing professional immediately. Louisiana uses judicial foreclosure, including an expedited executory process in qualifying cases. A general 60–120-day estimate is not a dependable deadline for your case; ask a Louisiana attorney to confirm the actual dates and available options.
Common questions
Can I list my Broussard property free to local investors?
Yes. You can list your home or land for sale by owner free on Home Posted to reach pre-screened investors and cash buyers searching Broussard and the surrounding area. You can also request a direct cash offer. Neither route guarantees an offer or a particular sale price.
Will a cash buyer purchase a home with flood or insurance problems?
Some will consider it, but not every buyer will. Cash removes a mortgage lender’s requirements, not the cost or risk of owning the property. Expect buyers to review flood exposure, past damage, repairs and insurance costs when deciding whether to offer and at what price.
Is owner financing better than taking a lower cash offer?
Not necessarily. A higher total price paid over time is different from money received at closing. Compare the down payment, payment reliability, servicing costs and default risk with the net proceeds of the cash offer. Have an attorney review the financing terms before you commit.
Can a Broussard sale close in seven days?
It may be possible when ownership is clear, payoff figures are ready and the buyer has available funds. Liens, succession matters or unresolved title issues can extend that timeline. Get a proposed closing date confirmed after the closing professional reviews the file.
Does a Louisiana notary handle every part of the closing?
Not necessarily. Notarization is important, but it does not replace title examination, payoff coordination, recording or funds handling. Ask the local closing professional who will perform each task and request an itemized explanation of charges.
List your house in Broussard, LA, free, with no percentage commission
Buyers search in Broussard, LA every day. Put your property in front of them, choose the offer types you will consider, and manage conversations in the platform.
- No listing fee or percentage commission
- Seen by buyers and investors