
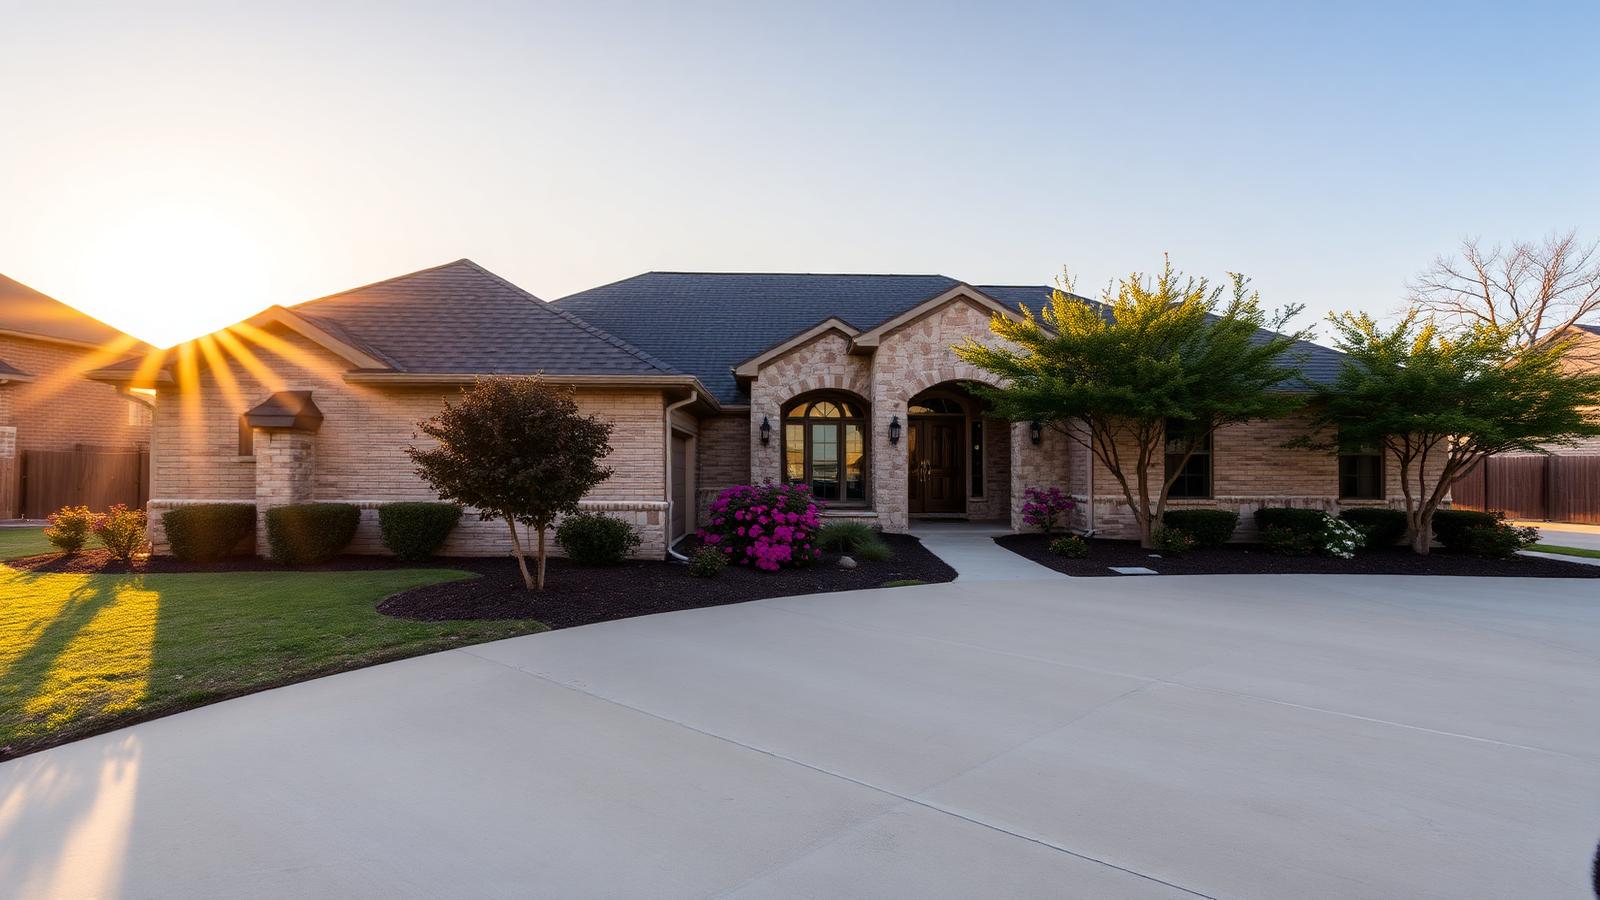

Local insights / Baton Rouge, LA
Baton Rouge homes: flood risk, buyer demand and the cost of waiting
An older raised cottage in the Garden District presents different selling questions from a rental near LSU or a slab-foundation home elsewhere in East Baton Rouge Parish. Condition, flood history and the cost of insuring the property can matter as much as the asking price. On Home Posted, owners can list free to reach pre-screened investors and cash buyers searching Baton Rouge, or request a direct cash offer.
Older cottages, campus rentals and suburban ranches
Baton Rouge has a varied housing stock: older cottages and bungalows in Mid City and the Garden District, postwar brick ranches, small rental properties near LSU, and newer subdivisions farther from the center. Buyers evaluating an older home often look closely at foundation movement, roof age, wiring, plumbing and past renovations, not just cosmetic repairs.
Location also changes how investors assess a property. Around LSU, rental history and existing leases can be important. Elsewhere, access to I-10 or I-12, the home's layout and the amount of work needed may shape a resale or rental plan. A statewide median value is not a useful substitute for recent nearby sales of comparable homes.
Who looks beyond a conventional mortgage sale?
Potential buyers include local landlords, renovation investors and regional buyers who search across Baton Rouge, New Orleans and Lafayette. Their plans differ: one may want a tenant-occupied property with documented income, while another needs a vacant home that can be repaired and resold.
A cash buyer does not need mortgage approval, which can remove one source of delay. Some investors will consider flood history, deferred maintenance or insurance complications that a financed buyer cannot accommodate. That does not mean those issues disappear: buyers may adjust their price, require inspections or decline the property. Share repair records, leases and known damage early so offers reflect the actual situation.
Flood history can reshape the deal before closing
The 2016 flooding remains relevant to many properties in and around Baton Rouge. Buyers may ask whether a home flooded, how repairs were completed and whether supporting records are available. A flood-zone designation alone does not tell the whole story, and being outside a high-risk mapped zone does not mean a property cannot flood.
Insurance quotes, lender requirements and inspection findings can delay a financed sale or change what a buyer can afford. Cash buyers may have more flexibility, but carrying costs still affect their calculations. Inherited ownership, unresolved liens and missing succession paperwork can also hold up a closing, regardless of how the buyer pays.
- Gather available flood-repair invoices, permits and elevation documentation.
- Provide roof age, known damage and available insurance information without promising a buyer's future premium.
- Ask a Louisiana closing professional to review ownership and title issues early.
Cash now or payments over time?
A cash offer may fit an owner who needs sale proceeds promptly, cannot fund repairs or wants to stop paying carrying costs. Compare the expected net proceeds, inspection rights, closing costs and proof of funds, not just the headline offer. A closing in as little as seven days may be possible with a ready buyer and clear title, but it is not guaranteed.
Owner financing means the seller accepts payments over time rather than receiving the entire price at closing. It may attract a different set of buyers, but the seller takes on repayment risk and may face collection or foreclosure costs if payments stop. It is not usually a simple solution to an urgent foreclosure deadline, particularly when an existing mortgage must be paid off. Have a Louisiana attorney review the proposed structure, existing loan restrictions and required documents, and ask a tax professional about the tax consequences.
Set the closing date around the actual parish paperwork
Louisiana foreclosure is judicial, but executory process can move more quickly than an ordinary lawsuit when its requirements are met. Do not treat a general 60–120-day estimate as the time you personally have left. Notices, court proceedings and any scheduled sheriff's sale determine the urgency. An attorney should review your specific deadline immediately if foreclosure is underway.
Louisiana sales use notarized transfer documents, but closing is more than choosing a notary and showing up to sign. A Louisiana title company or closing attorney commonly coordinates the title examination, payoff information, funds and recording with the East Baton Rouge Parish Clerk of Court. Tell the closing professional about any deadline before accepting an offer; title defects, succession work or lender payoff delays can prevent even a cash purchase from closing quickly.
Common questions
Can I list my Baton Rouge property free for local investors?
Yes. You can create a free for-sale-by-owner listing on Home Posted to reach pre-screened investors and cash buyers searching Baton Rouge. Include the condition, occupancy, known flood history and your preferred timeline. You can also request a direct cash offer; neither route guarantees an offer or a sale.
Will a cash buyer consider a house that flooded?
Some will, particularly when they can evaluate the repairs and future insurance costs. Provide available documentation and disclose known issues. Expect the buyer to account for repair needs and risk in the offer rather than ignore them.
Can a Baton Rouge cash sale close in seven days?
It may be possible if the buyer has available funds, title is clear and the closing documents and payoffs are ready. Inherited ownership, liens or an unresolved foreclosure can take longer. Confirm feasibility with the closing professional before relying on that date.
Does owner financing help me avoid paying off my existing mortgage?
Do not assume it does. Your existing loan may restrict transfers or require repayment when you sell. Owner financing also leaves you exposed to buyer default. Have a Louisiana attorney review the mortgage and proposed sale before agreeing to payment terms.
Do I just need a notary to close in Baton Rouge?
Notarization is part of the transaction, but it does not replace title review, mortgage payoffs, fund handling or recording. A Louisiana title company or closing attorney commonly coordinates these steps. Ask who will perform each task and what costs you are expected to pay.
List your house in Baton Rouge, LA, free, with no percentage commission
Buyers search in Baton Rouge, LA every day. Put your property in front of them, choose the offer types you will consider, and manage conversations in the platform.
- No listing fee or percentage commission
- Seen by buyers and investors