

Local insights / Monte Vista, CO
Monte Vista sellers: weigh a cash closing against payments over time
US 160 and US 285 meet in Monte Vista, but a house near downtown and an acreage outside town can attract very different buyers. In this part of the San Luis Valley, condition, winter heating costs, and access to water can matter more to a buyer than a statewide home-value figure. A useful selling plan starts with the property itself, and whether you need your proceeds at closing or can accept payments over time.
In-town homes and Rio Grande County acreage need different pitches
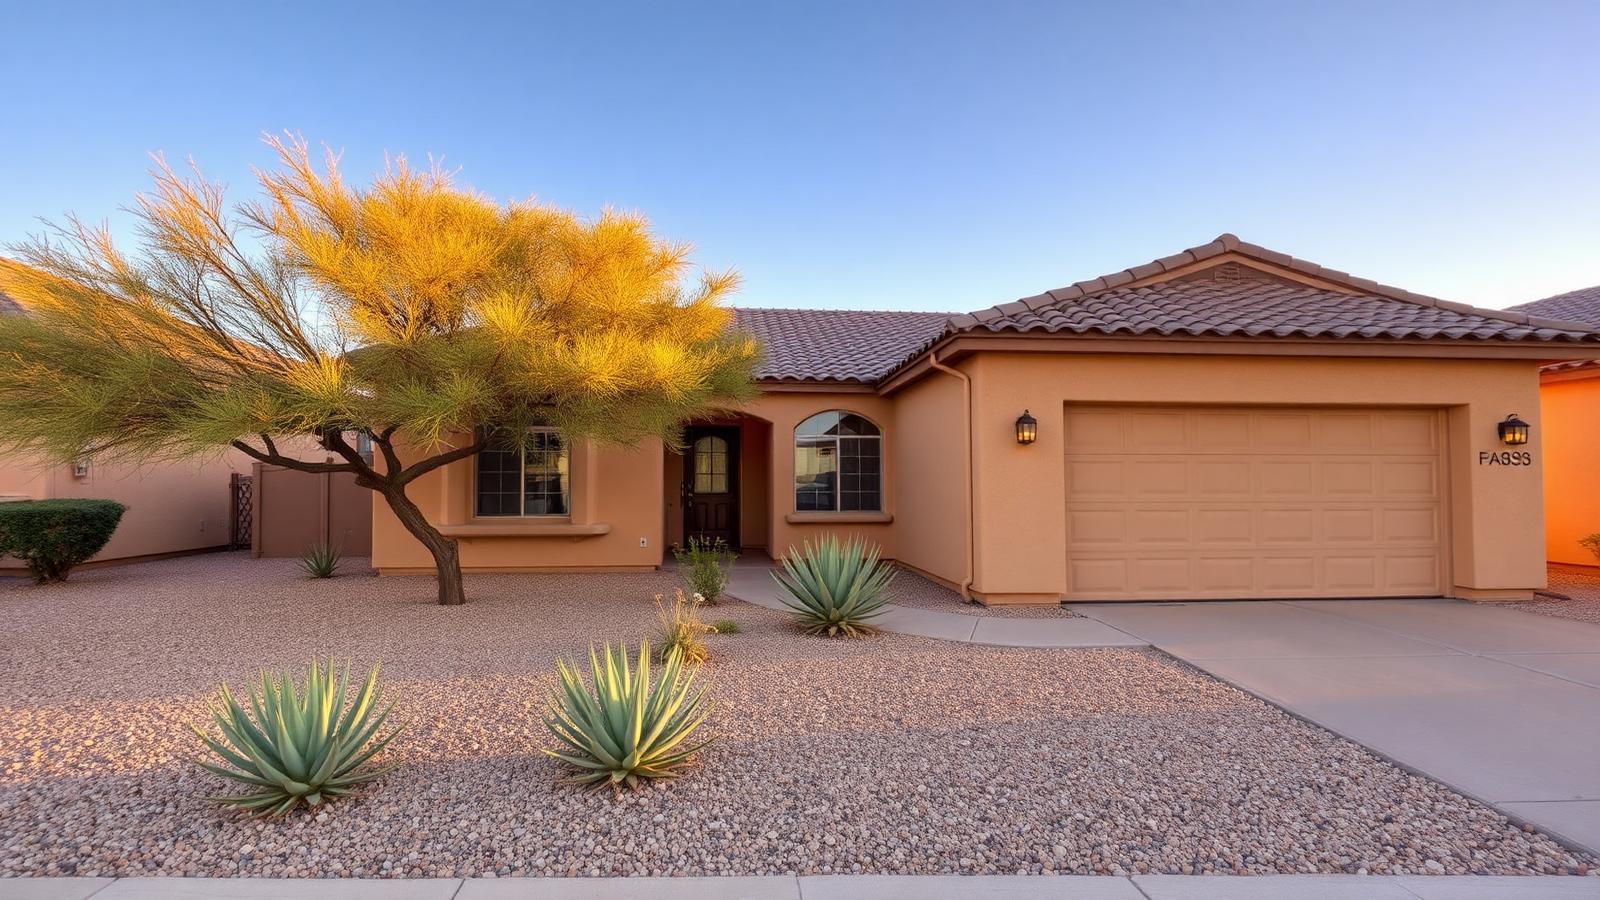
Monte Vista's housing includes older, modest-sized detached homes near the established town center, along with newer homes and rural properties beyond town. For an older house, buyers will want to understand the roof, electrical system, plumbing, insulation, and heating equipment. The San Luis Valley's cold winters make a home's heating setup and signs of freeze damage especially relevant.
On acreage outside Monte Vista, the questions shift toward legal access, outbuildings, septic systems, wells, and any irrigation rights represented as part of the sale. Identify what is actually included rather than describing a parcel simply as having 'water.' A Colorado water professional or attorney can help confirm rights and transfer requirements where those issues affect the transaction.
Look for San Luis Valley buyers, not Denver assumptions
Potential buyers include local households, people moving within the valley, rental investors, and purchasers seeking land or space for agricultural uses. Monte Vista's connection to the valley's potato farming and broader agricultural economy helps explain why usable acreage, storage buildings, and access can be important selling points. Nearby Alamosa and Del Norte are also relevant places to consider when marketing beyond town.
Monte Vista is in the San Luis Valley, not the Western Slope or the Front Range. Heavy investor activity in Denver or Colorado Springs does not establish how many offers a Monte Vista property will receive. Seek competing proposals where possible, but evaluate each buyer's funds, contingencies, and ability to close rather than assuming a particular number of bids.
The delays are often in the paperwork and property systems
An older home's repair needs can complicate a financed sale if the lender requires work before closing. For rural property, missing well records, uncertain access, septic concerns, or unclear boundaries can extend due diligence. Inherited ownership, liens, and unresolved title issues can delay either a cash sale or a financed one.
Colorado residential closings are commonly handled by a title company, and an attorney generally is not required for a routine sale. The title company coordinates title work, payoff figures, signing, recording, and disbursement. Funds are released when closing requirements are satisfied, not necessarily the moment you sign. Confirm wiring instructions through a trusted phone number before sending money or sensitive information.
- Gather mortgage payoff information and any lien or foreclosure notices.
- Collect available repair records, utility information, and property disclosures.
- For rural parcels, locate well, septic, survey, and access documents before negotiations.
Cash now or a buyer's promise to pay over time?
A cash offer can suit an owner who needs a clean exit, wants to avoid lender-required repairs, or cannot keep carrying the property's expenses. Compare net proceeds after payoffs, fees, and any agreed credits, not just the advertised offer. A straightforward cash transaction may close in roughly 10–14 days after acceptance, but title issues, buyer verification, and other conditions can extend that schedule.
Owner financing means receiving some or much of the purchase price over time instead of receiving all proceeds at closing. It may broaden the buyer pool, but it also makes you a creditor with collection and default risk. A higher contract price is not automatically a better outcome than cash. Before agreeing, have a Colorado real estate attorney review the structure, any existing mortgage restrictions, required disclosures, security documents, and default provisions; ask a tax professional about the tax consequences.
- Cash offer: check proof of funds, earnest money, inspection rights, and closing conditions.
- Owner financing: evaluate the down payment, payment schedule, buyer's repayment capacity, and any balloon payment.
- Either route: compare the likely net proceeds with the time, expense, and risk you retain.
Use the foreclosure deadline, not a promised closing speed
Colorado generally uses a nonjudicial Public Trustee foreclosure process. The commonly cited roughly 110–125-day window relates to the scheduled sale after the Notice of Election and Demand is recorded for many nonagricultural properties; it is not a guaranteed amount of time remaining for every seller. Agricultural classifications, postponements, and case-specific circumstances can change the timetable. Confirm your actual dates with the Rio Grande County Public Trustee and seek legal advice promptly.
On Home Posted, you can list your Monte Vista house or land for sale by owner free to reach pre-screened investors and cash buyers searching the area. You can also request a direct cash offer. Neither option guarantees an offer or a closing date. If a foreclosure sale is approaching, tell prospective buyers and the title company immediately so they can assess whether a sale and payoff can be completed in time.
Common questions
Can I list my Monte Vista property free to local investors?
Yes. You can create a free for-sale-by-owner listing on Home Posted to reach investors and cash buyers searching Monte Vista and the surrounding area. Include the condition, occupancy, access, and relevant well or septic details. You can also request a direct cash offer; listing does not guarantee buyer interest.
Should I accept cash or offer owner financing?
Cash is generally the simpler option when you need proceeds at closing and do not want ongoing repayment risk. Owner financing may suit an owner who can wait for payments and understands the risk of buyer default. Compare the cash offer's net proceeds with the proposed financing terms, then have an attorney and tax professional review the owner-financing arrangement.
Can a Monte Vista cash sale close on a timeline set by the offer and title work?
That may be possible after acceptance when the buyer has verified funds, title is clear, and required documents and payoffs are ready. Inherited ownership, liens, rural access questions, or water-related due diligence can take longer. Get a written closing schedule rather than relying on a general speed claim.
Does Colorado's statewide median home value tell me what my home is worth?
Not reliably. Monte Vista pricing needs comparable local sales with similar size, condition, lot characteristics, and property type. A statewide figure blends very different markets. Rural acreage with water or outbuildings also needs a different comparison from an in-town house.
Do I need an attorney to close, especially if foreclosure has started?
An attorney generally is not required for a routine Colorado sale, and a title company commonly handles closing. However, foreclosure deadlines, disputed ownership, water rights, or owner financing are good reasons to obtain legal advice. A purchase contract alone does not stop a scheduled foreclosure sale.
List your house in Monte Vista, CO, free, with no percentage commission
Buyers search in Monte Vista, CO every day. Put your property in front of them, choose the offer types you will consider, and manage conversations in the platform.
- No listing fee or percentage commission
- Seen by buyers and investors