
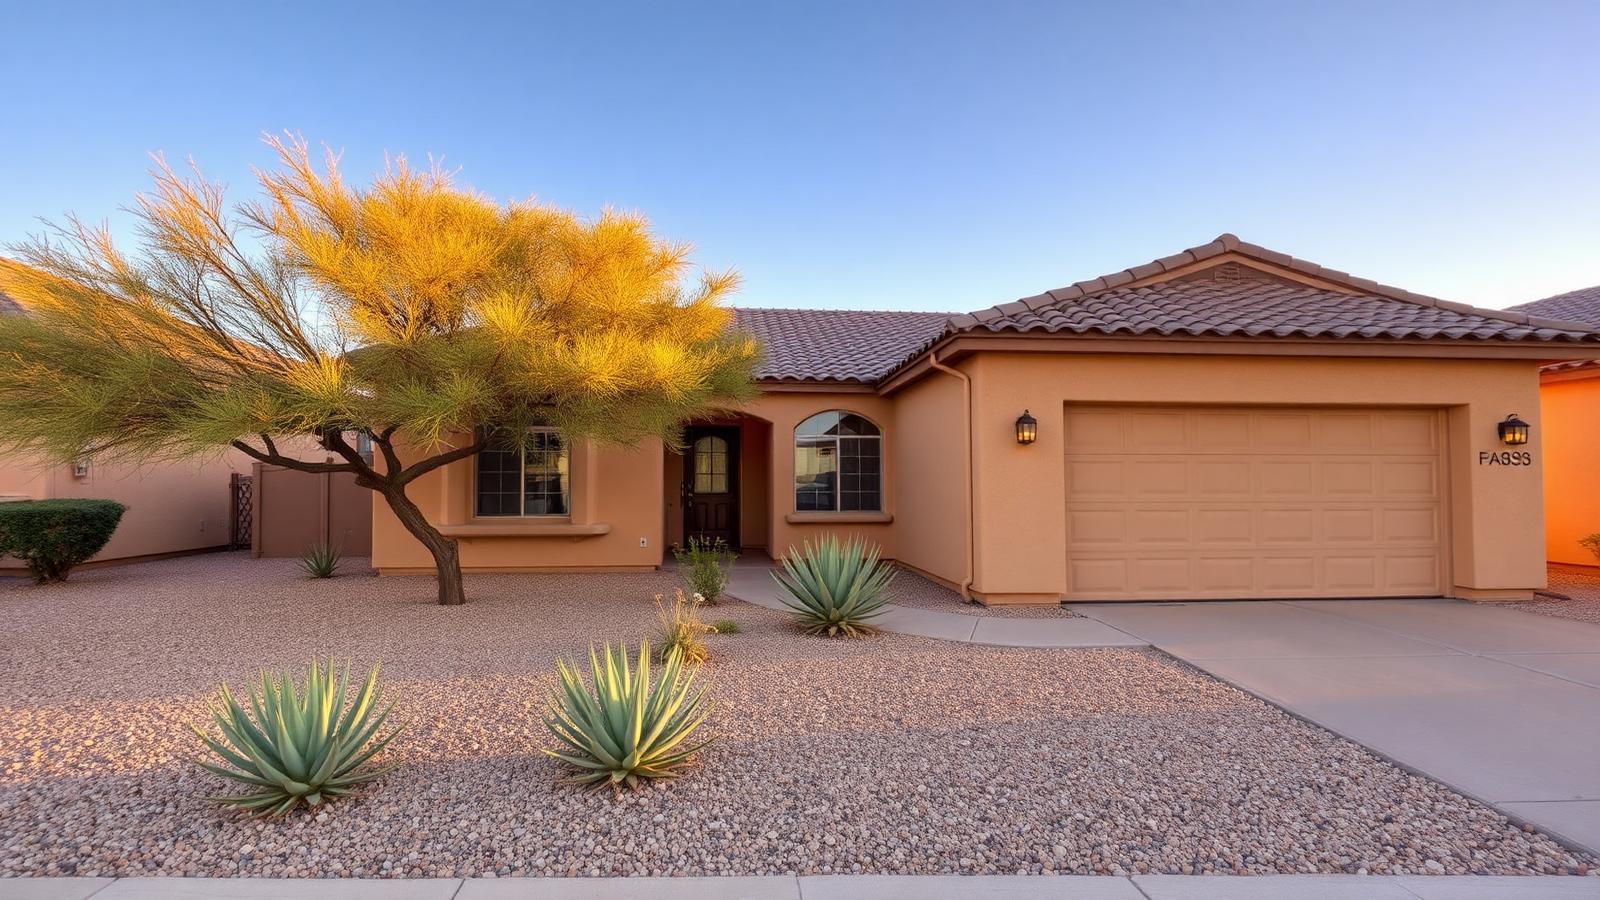

Local insights / Fruita, CO
Fruita homes, acreage and the trade-off between cash and seller financing
Fruita’s older homes near downtown and irrigated properties outside town need different sales pitches. Access to I-70 and nearby Grand Junction matters to some buyers; land use, irrigation and upkeep matter more to others. On this part of the Western Slope, reaching buyers who understand the property can matter more than collecting an offer quickly.
A downtown home is not priced like irrigated acreage
Fruita’s housing includes older detached homes around downtown, newer subdivision houses and rural residential properties around the edges of town. For an older house, buyers will look closely at roof condition, heating, electrical work and any additions. In a subdivision, HOA obligations and the condition of nearby comparable homes can influence the decision.
Acreage adds another layer: access, outbuildings, septic systems where present, and the source and availability of irrigation water. Make clear what is included rather than assuming a buyer understands the setup. Colorado’s statewide median home value is not a reliable asking-price shortcut for a particular Fruita property; comparable sales should match the location, condition and land characteristics.
The Western Slope buyer pool rewards a targeted listing
Potential buyers include households looking for access to Grand Junction, investors evaluating long-term rental income, and renovation buyers looking for a workable repair budget. Fruita’s access to Colorado National Monument and the nearby Kokopelli trail network can also attract lifestyle buyers. Those attractions do not, by themselves, establish rental income or permission for short-term rentals.
Western Slope cash-buyer markets are thinner than Denver or Colorado Springs. Multiple competing offers are worth seeking, but they are not assured. Owners can list free on Home Posted to reach pre-screened investors and cash buyers searching Fruita and Mesa County, and can also request a direct cash offer. Wider exposure gives you a way to test an offer rather than treating the first response as the market price.
Water questions and missing paperwork can stall a deal
For properties with land, uncertainty about irrigation arrangements, recorded access or property boundaries can slow a buyer’s review. A rural address may also raise questions about septic records and permitted improvements. Gather the documents you have early, and identify unanswered questions instead of making promises about water, development potential or permitted uses.
Within town, repair surprises, unpermitted additions, HOA documents and title issues can delay an otherwise straightforward sale. Colorado transactions commonly close through a title company; an attorney is not generally required for a routine closing. The title company coordinates signing, payoff and recording requirements, then disburses funds once closing conditions are satisfied. Confirm wiring instructions through a trusted phone number.
- Collect irrigation information and any water-related agreements that apply.
- Locate permits and records for additions, outbuildings or septic work.
- Request mortgage payoff information and disclose known liens.
- Describe repairs and occupancy accurately so buyers can price the actual situation.
Cash now or payments over time: compare the obligation
A cash offer may fit an owner who needs sale proceeds at closing, wants to avoid lender-related delays or does not want to manage payments afterward. A straightforward cash transaction may close on a timeline set by the offer and title work after acceptance, but title work, access, payoff requirements and the buyer’s terms can extend that window. Compare net proceeds, inspection rights, proof of funds and whether the contract can be assigned, not just the headline price.
Owner financing means accepting payments over time and taking on the risk that the buyer stops paying. It may widen the pool for certain properties, but a higher purchase price is not automatically a better outcome. Before agreeing, have a Colorado real estate attorney review the structure, security documents and any existing mortgage restrictions, and ask a tax professional about the consequences. Use a title company and discuss professional loan servicing rather than relying on an informal payment arrangement.
A Public Trustee deadline changes the decision
Colorado generally uses a nonjudicial Public Trustee foreclosure process. The often-cited roughly 110–125-day period is a foreclosure-process estimate, not a typical Fruita selling timeline or a promise of time remaining. Mesa County Public Trustee notices and the facts of the case determine the relevant dates; some of that window may already have passed before an owner starts considering a sale.
Do not assume a purchase contract pauses foreclosure or that a proposed quick closing will beat the scheduled sale. Ask the title company to confirm payoff and closing requirements promptly, and speak with a Colorado attorney or a HUD-approved housing counselor about deadlines and options. Owner financing is not a substitute for resolving the existing debt and obtaining any necessary approvals.
Common questions
Can I list my Fruita property free to local investors?
Yes. You can create a free for-sale-by-owner listing on Home Posted to reach qualified independent buyers and investors searching Fruita and the surrounding area. Include the condition, occupancy, acreage and irrigation details where relevant. You can also request a direct cash offer; neither route guarantees an offer or a sale.
Should I expect several cash offers in Fruita?
It is worth seeking competing offers, but Fruita has a smaller investor pool than Front Range markets. The number of responses depends on price, condition, property type and exposure. Compare each buyer’s funding, contingencies, closing costs and proposed closing date alongside the price.
Can a cash buyer close on a timeline set by the offer and title work?
That may be possible after acceptance for a straightforward transaction with clear title and ready funds. Liens, probate, missing signatures, occupancy arrangements or unresolved property questions can require more time. Have the buyer and title company confirm a realistic schedule.
Does owner financing make sense if I still have a mortgage?
An existing mortgage can complicate seller financing, including restrictions that may allow the lender to demand repayment following a transfer. Do not assume you can simply keep making the old payments while collecting new ones. A Colorado real estate attorney should review the loan documents and proposed transaction before you commit.
Who handles the closing in Fruita?
A title company commonly handles Colorado closings, including title review, document signing, recording coordination and disbursement. An attorney is not generally required for a routine sale, but legal review is valuable for owner financing, foreclosure deadlines or disputed ownership. Ask when funds will be released rather than assuming signing alone triggers payment.
List your house in Fruita, CO, free, with no percentage commission
Buyers search in Fruita, CO every day. Put your property in front of them, choose the offer types you will consider, and manage conversations in the platform.
- No listing fee or percentage commission
- Seen by buyers and investors