
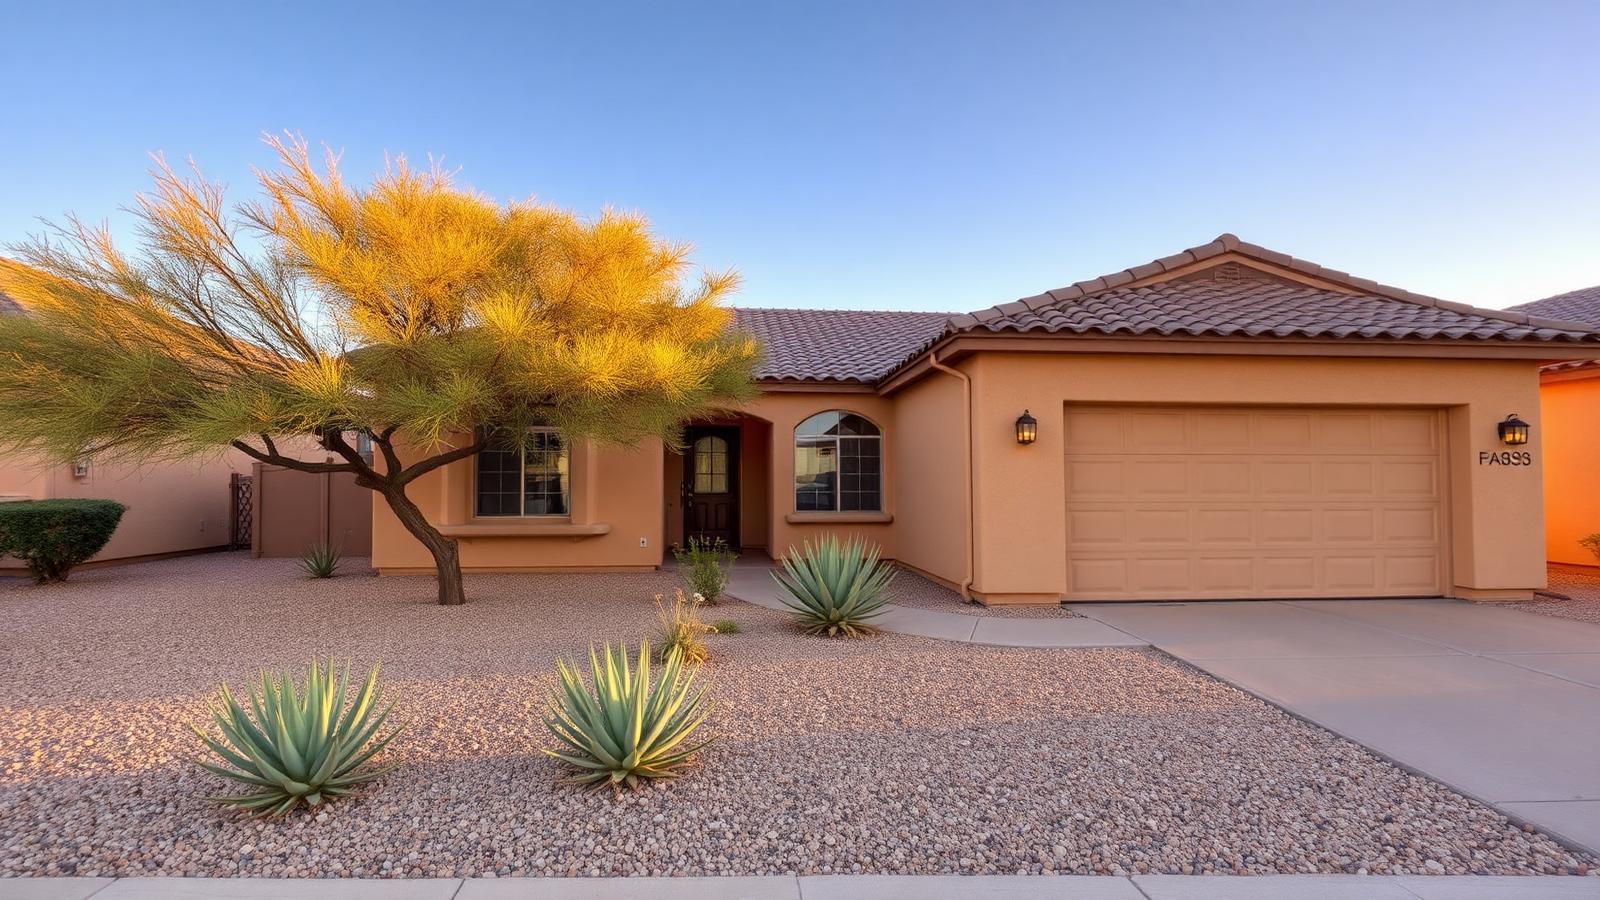

Local insights / Dacono, CO
Dacono sellers: weigh a cash closing against monthly payments
Highway 52 connects Dacono to I-25, putting this Weld County community within reach of buyers searching beyond Denver. But an older home in the Glens of Dacono and a newer subdivision house can attract different offers, and different financing obstacles. The useful comparison is not just the advertised price, but what you receive at closing, what you must fix, and what risk you keep afterward.
The Glens and newer subdivisions need different pricing
Dacono’s housing stock includes older site-built houses, manufactured homes in the Glens of Dacono, and newer detached homes. Buyers may also compare properties in neighboring Frederick and Firestone. Recent sales of similar nearby properties are more useful than Colorado’s statewide median, especially when construction type, lot ownership, and condition differ.
For a manufactured home, establish whether the sale includes the land and how the home is titled before discussing financing. Foundation documentation and real-property status can affect a buyer’s loan options. For newer homes, HOA obligations, property taxes, and competition from nearby new construction can influence what buyers are willing to pay.
Reach beyond one Front Range cash buyer
Dacono can draw owner-occupants looking along the I-25 corridor, rental investors evaluating long-term income, and renovation buyers looking for properties that need work. These buyers calculate value differently: a landlord focuses on rent and ongoing costs, while a renovation buyer deducts repairs, holding expenses, and resale risk.
Access to the Denver-area investor market makes it worth seeking competing proposals, but it does not guarantee multiple offers. On Home Posted, you can list your Dacono house or land free to reach investors and cash buyers searching the area, or request a direct cash offer. Compare proof of funds, contingencies, earnest money, and your expected proceeds, not just the headline amount.
Title details can matter more than the moving date
A cash purchase avoids mortgage underwriting, but it does not bypass ownership problems. Unresolved liens, an estate with incomplete paperwork, manufactured-home title issues, or questions about additions can delay a Dacono closing. HOA documents and unpaid assessments may also need attention. Gathering deeds, loan payoff information, and available permit records early helps identify obstacles.
Colorado residential transactions commonly close through a title company; an attorney is not generally required for a routine sale. The title company coordinates title work, payoffs, signing, and disbursement. A straightforward cash purchase may close on a timeline set by the offer and title work after acceptance if title is clear and everyone is ready, but that is not a guaranteed deadline. Confirm funding timing and verify wire instructions directly with the closing company.
A Weld County foreclosure clock is not extra time
Colorado commonly uses a nonjudicial Public Trustee foreclosure process. For many nonagricultural properties, the scheduled sale falls roughly 110–125 days after the Notice of Election and Demand is recorded. That is a process window, not a promise that a seller has that much time remaining when they first seek help. Your recorded notices and actual sale date matter.
For a Dacono property facing foreclosure, confirm the timeline with the Weld County Public Trustee and discuss your options with a Colorado foreclosure attorney or HUD-approved housing counselor. Ask the title company to obtain current payoff figures promptly. Listing the property or accepting an offer does not itself stop foreclosure, and even a short cash closing needs enough time to resolve title and funding.
Cash resolves the sale; owner financing keeps you involved
A cash offer generally suits an owner who needs proceeds at closing, wants to avoid carrying the property, or does not want responsibility for collecting payments. The trade-off may be a lower price in exchange for fewer financing conditions and less repair work. Review the actual contract: a cash label alone does not rule out inspections, cancellation rights, or delays.
Owner financing may appeal when you do not need all the money immediately and a buyer can provide an acceptable down payment and repayment plan. But you become the lender, with exposure to missed payments, collection costs, and the property’s future condition. An existing mortgage can complicate the arrangement. Have a Colorado real estate attorney assess the structure and applicable lending requirements, and ask a tax professional about the consequences before agreeing.
- Compare cash proceeds after payoffs and closing costs with the owner-financing down payment and future payments.
- Evaluate the buyer’s ability to repay rather than accepting a higher purchase price at face value.
- Discuss loan servicing, insurance, taxes, default procedures, and any balloon payment with qualified professionals.
Common questions
Can I list my Dacono property free to local investors?
Yes. Owners can list a house or land free on Home Posted to reach investors and cash buyers searching Dacono and the surrounding Front Range. Include the property type, condition, occupancy, and whether land is included with a manufactured home. You can also request a direct cash offer; neither option guarantees an offer or sale.
Does a manufactured home in the Glens need different sale paperwork?
It can. The title company needs to establish ownership of the home and any included land, along with how the home is titled. A financed buyer may also need foundation and real-property documentation. Identify those requirements before setting a firm closing date.
Can a Dacono cash sale close on a timeline set by the offer and title work?
A straightforward transaction may close within that period after acceptance, provided the buyer has funds available and title, payoffs, and signing arrangements are ready. Liens, estate issues, or manufactured-home documentation can extend the timeline.
Is owner financing a good solution if I am behind on my mortgage?
Do not assume it resolves the existing loan or stops foreclosure. The mortgage payoff, loan terms, and foreclosure deadline need professional review. Speak with a Colorado attorney and the title company before offering financing to a buyer.
Should I accept the first cash offer I receive?
Not automatically. If your deadline allows, seek another proposal and compare net proceeds, proof of funds, contingencies, and closing dates. Dacono’s access to Front Range buyers makes broader exposure worthwhile, but the number and quality of offers will depend on the property and asking terms.
List your house in Dacono, CO, free, with no percentage commission
Buyers search in Dacono, CO every day. Put your property in front of them, choose the offer types you will consider, and manage conversations in the platform.
- No listing fee or percentage commission
- Seen by buyers and investors